
On Friday, Kevin Warsh, the chair of the U.S. Federal Reserve, stated that inflation levels remain excessively high, indicating that the central bank might need to increase interest rates in the upcoming months to address this issue. This was a more definitive message regarding his economic perspective compared to his earlier remarks.
During his inaugural prominent address at the Fed’s annual gathering in Jackson Hole, Wyoming, Warsh recognized that recent U.S. data suggests a slight easing of inflation; however, he remarked, “they do not indicate that the underlying trends have significantly improved.”
“We need to ensure that underlying inflation is progressing towards our goal clearly and at an adequate pace,” Warsh stated.
“If not, we have tasks ahead of us.”
Warsh’s address, delivered after he succeeded Jerome Powell at the end of May following the conclusion of Powell’s term, was eagerly awaited. As the Canadian economy approaches its own challenges, the U.S. economy is also grappling with significant obstacles related to its debt and disruptions arising from tariff policies—issues that Warsh had to navigate during his speech.
The new Fed chair’s remarks seemed to reassure Wall Street that tackling inflation remains a central focus for the bank. While he did not suggest that an interest rate hike was imminent, he also appeared to reject the notion that inflation is no longer a concern.
He highlighted data showing that inflation continues to stay stubbornly above the Fed’s target of two percent.
Central banks typically raise interest rates to manage prices during inflation, but both the Bank of Canada and the U.S. Federal Reserve have recently cut rates. Additionally, Trump’s recent move to ‘terminate’ Canada-U.S. trade negotiations has raised questions.
Following Warsh’s speech, the U.S. stock market remained stable, yet expectations in the bond market are growing for the Fed to increase interest rates. The yield on the two-year Treasury, which closely aligns with predictions for the Fed’s actions regarding its federal funds rate, rose from 4.22 percent to 4.30 percent, indicating that investors anticipate a rise in short-term yields.
Conversely, longer-term yields on 10-year and 30-year Treasuries remained relatively unchanged, suggesting that investors do not foresee the need for elevated rates over an extended period to manage inflation.
No ‘forward guidance’ from Warsh
According to Jon Faust, an economist at Johns Hopkins University and a former adviser to Powell, Warsh effectively communicated a firmer approach to inflation while simultaneously avoiding the detailed guidance that his predecessors typically provided, which he has criticized.
“He managed to express that he would support a rate hike if necessary, which was a concern for many,” Faust noted.
However, Michael Strain, who directs economic policy studies at the American Enterprise Institute, commented that the Fed chair has previously spoken firmly about inflation without enacting a hike in the Fed’s primary rate. His comments on Friday did not provide clearer insights regarding the timeline for any Fed actions, he added.
This crucial speech arises amid rising uncertainties on Wall Street regarding Warsh’s commitment to combat inflation.
Concerns over this issue may have contributed to increasing bond yields, which can elevate borrowing costs for the government and others. Nonetheless, Warsh expressed his reluctance to offer what analysts refer to as “forward guidance” regarding whether the Fed will raise, lower, or maintain rates in future meetings, arguing that doing so would restrict the Fed’s flexibility by binding it to a particular policy.
Several economists contend that he could elaborate on his perspectives regarding Fed policy without revealing his intentions about future actions.
U.S. inflation cooled in June
Warsh’s statements do not necessarily indicate that the central bank will increase rates at its next meeting scheduled for mid-September. However, his remarks implied that current rates might not be sufficient to lower inflation to the Fed’s target of two percent.
As a general guideline, interest rates often need to reach a level that limits borrowing and spending to mitigate inflation.
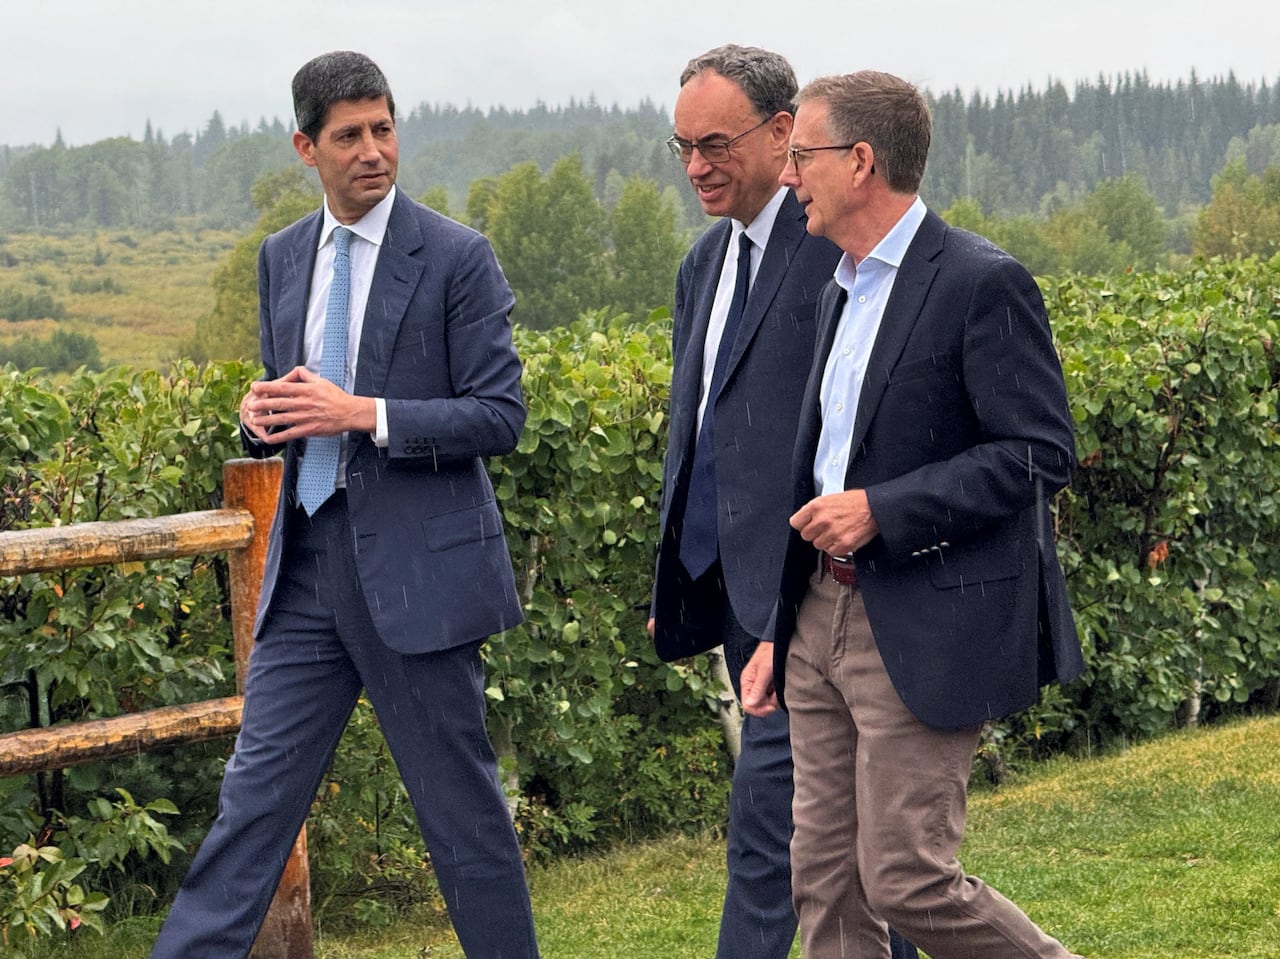
Warsh, left, is seen walking with Bank of Canada Governor Tiff Macklem, right, and Bank of England Governor Andrew Bailey during the Kansas City Fed’s annual economic symposium in Jackson Hole, Wyo., on August 28. (Ann Saphir/Reuters)
Warsh pointed out that over the past year, 54 percent of the goods and services monitored by the government have experienced price hikes of three percent or more. Although this figure is an improvement from pandemic high levels, it remains “well above” the 32 percent that recorded similar increases in the two decades preceding the pandemic.
However, he indicated that current interest rates do not seem to be restricting economic activity, citing strong business investments in AI technologies and infrastructure, as well as vigorous consumer spending.
Inflation has eased in June and July after a spike in May due to rising gas prices, yet it still exceeds the central bank’s target.
Historically, Fed chairs have utilized speeches at Jackson Hole to address overarching topics regarding interest-rate policy and the economy or to hint at forthcoming modifications in their strategies. In 2022, as pandemic-related inflation surged to 9.1 percent, Powell indicated that the Fed would persist in significantly increasing interest rates to combat rampant prices, acknowledging that such actions would result in “pain” for consumers and businesses.
Currently, Wall Street investors estimate the likelihood of a rate hike at the Fed’s upcoming meeting on September 15 and 16 to be nearly a coin toss, according to futures pricing monitored by CME FedWatch, up from prior assessments that suggested a one-third chance of an increase.